

nobuy
CLCF0
LanguageENG
PublishYear1999
publishCompany
Cambridge University Press
EISBN
9780511035524
PISBN
9780521624138
- Product Details
- Contents
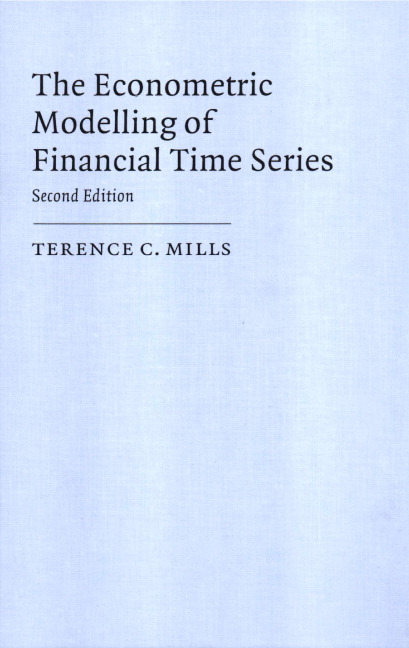
Substantially revised and updated second edition of Terry Mills' best-selling graduate textbook The Econometric Modelling of Financial Time Series. The book provides detailed coverage of the variety of models that are currently being used in the empirical analysis of financial markets. Covering bond, equity and foreign exchange markets, it is aimed at scholars and practitioners wishing to acquire an understanding of the latest research techniques and findings, and also graduate students wishing to research into financial markets. This second edition includes a great deal of new material, and also provides a more in-depth treatment of two crucial, and related, areas: the theory of integrated processes and cointegration. The new material discusses the distributional properties of asset returns and more recent and novel techniques of analysing and interpreting vector autoregressions that contain integrated and possibly cointegrated variables. Data appendix available online at www.lboro.ac.uk/departments/ec/cup.
Collected by
- Yale University
- University of Melbourne Library
- Columbia University Library
- Stanford University
- University of Chicago
- UCB


