

未购
中图号O21
语种ENG
出版年2013
出版信息
Cambridge University Press
EISBN
9781107440418
PISBN
9781107039759
- 介绍
- 目录
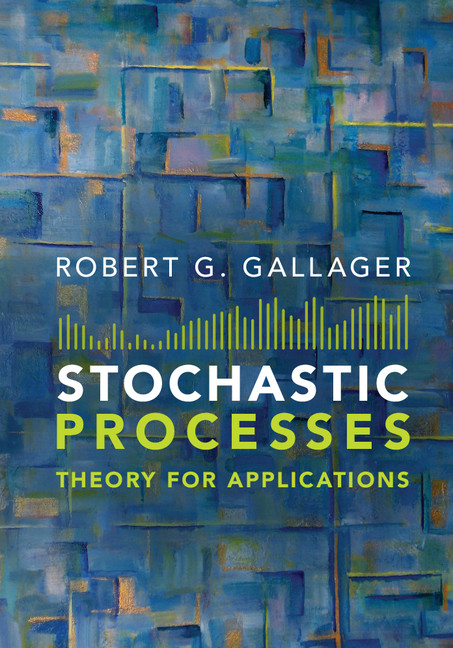
This definitive textbook provides a solid introduction to discrete and continuous stochastic processes, tackling a complex field in a way that instils a deep understanding of the relevant mathematical principles, and develops an intuitive grasp of the way these principles can be applied to modelling real-world systems. It includes a careful review of elementary probability and detailed coverage of Poisson, Gaussian and Markov processes with richly varied queuing applications. The theory and applications of inference, hypothesis testing, estimation, random walks, large deviations, martingales and investments are developed. Written by one of the world's leading information theorists, evolving over twenty years of graduate classroom teaching and enriched by over 300 exercises, this is an exceptional resource for anyone looking to develop their understanding of stochastic processes.
机构馆藏
- 加州大学洛杉矶分校
- 芝加哥大学
- 哈佛大学
- 剑桥大学
- 加州大学伯克利分校
- 香港中文大学
- 斯坦福大学
- 牛津大学
- 麻省理工大学
- 普林斯顿大学
- 耶鲁大学


